
Listen: the breakdown
Developing story update (September 27, 2026, 15:01 UTC):
An update for traders watching this story: long-term U.S. Treasury yields have now pushed to 5.5%. That is the market repricing the same fiscal stress we flagged, and rising yields raise the cost of servicing an already ballooning debt load, which can reinforce the pressure rather than relieve it.
The divergence is also sharpening. While the U.S. debt-to-GDP ratio keeps climbing rapidly, based on our sources several other heavily indebted economies including Italy and Greece are holding steady or reducing their burdens, leaving the U.S. increasingly alone on this trajectory.
Crypto is still not treating this as an immediate catalyst. Bitcoin and Ether remain roughly flat over the last 24 hours, so this stays a structural macro backdrop to track rather than a live trigger for a move.
What to watch now: Whether long-term Treasury yields hold above 5.5% and start pulling capital away from risk assets, or eventually push liquidity toward scarce assets.
Developing story update (September 27, 2026, 14:40 UTC):
Update: fresh data sharpens the foreign-demand picture behind this story. Foreign central bank Treasury holdings are now down $67 billion over the 12 months through July, part of a $587 billion decline since their 2015 peak. Their combined share of marketable Treasuries outstanding has slipped to 3.0%, the lowest reading since 1993.
The stress is showing up in prices as well. The $32 trillion Treasury market is on track for its worst monthly performance since late 2024, based on our sources. For traders, this is the mechanism to watch: as foreign buyers step back, more issuance has to clear through domestic and price-sensitive hands, which tends to push yields and funding costs higher.
Crypto is not reacting on the day, with BTC around $84.7K and ETH near $2,692, both roughly flat. The relevance stays macro and structural: a Treasury market that has to work harder to fund persistent deficits strengthens the longer-term case for scarce, non-sovereign assets as a hedge, even without an immediate price catalyst.
What to watch now: Whether Treasury yields and monthly performance keep deteriorating as foreign central bank demand shrinks toward multi-decade lows.
Developing story update (September 27, 2026, 13:38 UTC):
Update: the pressure our sources flagged is now showing up directly in the bond market. The roughly $32 trillion U.S. Treasury market is on track for its worst monthly performance since late 2024, as long-term yields grind higher and 30-year mortgage rates push near 7.5%. The mechanism is simple supply versus demand: new debt issuance is running around three trillion dollars per quarter, and that is outpacing what buyers worldwide are willing to absorb.
For traders this sharpens the same read, not a new one. Higher yields are a near-term headwind for risk assets, so short bursts of pressure on BTC and ETH remain likely if rates keep climbing. Longer term, a Treasury market visibly struggling to place supply is exactly the backdrop that can push some capital toward harder, non-sovereign stores of value over time. BTC near $85,020 and ETH near $2,711 are still trading independently of this macro thread today.
What to watch now: Whether long-end Treasury yields and mortgage rates keep rising into month-end, which would extend the near-term headwind for BTC and ETH.
Developing story update (September 27, 2026, 13:17 UTC):
Update: fresh figures put foreign central banks’ combined share of marketable Treasuries outstanding at just 3.0%, based on our sources. That quantifies how far these official holders have already stepped back, and it sits alongside the same run of data we reported: a $13 billion cut in July, a $67 billion reduction over the year to July, and a cumulative $587 billion decline since the 2015 peak.
For traders the read is unchanged in direction. A shrinking official-sector footprint in Treasuries leaves more supply for price-sensitive buyers, which tends to keep upward pressure on yields and, with it, the cost of capital that typically weighs on risk assets. Bitcoin and Ethereum remain roughly flat over the last 24 hours, so there is no immediate reaction priced in yet.
What to watch now: Whether the foreign central bank share of Treasuries slips further below 3.0% in the next monthly data.
Developing story update (September 27, 2026, 12:10 UTC):
Foreign central banks reduced Treasury holdings by $13 billion in July, contributing to a $67 billion reduction over 12 months. The cumulative decline since 2015 now stands at $587 billion, with their share of marketable Treasuries at 3.0%. This quantifies the ongoing shift away from U.S. debt.
The $32 trillion U.S. Treasury market is experiencing its worst monthly performance since late 2024. Long-Term Treasury Yields have climbed to 5.5%, directly impacting borrowing costs across the economy.
Mortgage rates have also risen to 7.5%, signaling broader economic pressure. Traders should continue to monitor these trends for potential implications on capital flows and the stability of traditional financial markets.
What to watch now: Monitor further shifts in foreign Treasury holdings and the Federal Reserve's response to rising yields and market volatility.
Developing story update (September 27, 2026, 10:43 UTC):
Fresh data puts a sharper frame on the demand story: foreign central banks now hold just 3.0% of all marketable Treasuries outstanding, a shrinking footprint that helps explain why the market is leaning harder on price-sensitive private buyers to absorb new supply.
The pressure is now showing up in prices, not just flows. The roughly $32 trillion Treasury market is on track for its worst monthly performance since late 2024, based on our sources. Weaker demand meeting relentless issuance tends to push yields higher, which historically tightens financial conditions and can act as a headwind for risk assets, crypto included, if the move extends.
What to watch now: Whether Treasury weakness deepens into month-end and lifts yields enough to pressure BTC and ETH.
Developing story update (September 27, 2026, 10:22 UTC):
Fresh figures break out the official sector specifically, and they sharpen the picture. Foreign central banks cut their U.S. Treasury holdings by roughly $13 billion in July alone, and by about $67 billion over the twelve months through July. This is the buyer segment that traditionally anchors demand for government debt, so its retreat matters more than a headline percentage.
The pullback is structural, not a one-month blip: central bank holdings are now down around $587 billion from their 2015 peak. For traders, a multi-year fade in official demand is one of the conditions that can keep upward pressure on yields and reinforce the longer-term debasement narrative that tends to favor scarce assets like Bitcoin, though rising yields can still weigh on risk appetite in the near term.
What to watch now: Whether official-sector selling accelerates in the next monthly Treasury holdings data or stays a slow structural bleed.
Developing story update (September 27, 2026, 09:18 UTC):
Update: the strain is now showing up directly in market pricing, not just in the flow data. Long-term Treasury yields have climbed to 5.5% and the roughly $32 trillion Treasury market is on track for its worst monthly performance since late 2024, based on our sources. This is the demand story translating into higher borrowing costs across the curve.
For traders, the pass-through is what matters: mortgage rates have moved up to 7.5%, tightening financial conditions for households and pressuring rate-sensitive assets. Higher-for-longer yields tend to compete with risk assets for capital in the near term, so watch whether this rise stalls the current mild bid in BTC and ETH or eventually strengthens the longer-run case for holding assets outside the fiat debt system.
What to watch now: Whether the 5.5% long-yield move stalls out or keeps climbing, and how BTC/ETH react as financial conditions tighten.
Developing story update (September 27, 2026, 07:54 UTC):
Update: the picture on foreign demand has sharpened. Foreign central banks now hold just 3.0% of all marketable Treasuries outstanding, a shrinking footprint that underlines how far the traditional buyer base has stepped back.
The pressure is showing up in price. The roughly 32 trillion dollar Treasury market is now tracking its worst monthly performance since late 2024, based on our sources, as weaker demand pushes yields higher and lifts the government’s borrowing costs. For traders this keeps the same structural setup in view: sustained stress in sovereign debt tends to strengthen the long-term case for scarce, non-sovereign assets like Bitcoin, even when the immediate price reaction is muted.
What to watch now: Watch whether the Treasury selloff deepens into month-end and whether the foreign central bank share keeps sliding below 3.0%.
Market briefing: Foreign net buying of US Treasuries fell 58% in the year through July, roughly $410 billion less demand, while the same money poured into US equities. BTC held near $84,548 as the market treated it as a slow-burn story, not a same-day shock.
- Foreign net Treasury buying fell 58% in the year through July, about $410 billion less.
- The same foreign investors made a record $942 billion in net US equity and fund purchases.
- Fading demand for US debt raises the long-run odds of Fed liquidity support, a tailwind for scarce assets.
Source: U.S. Congressional Budget Office
Foreign Treasury buying just fell 58% in a year, roughly $410 billion less demand for US debt. If Washington needs replacement buyers, who pays the higher yield, and where does that leave Bitcoin?
The numbers under America's borrowing habit are starting to move. Foreign net buying of US Treasuries fell 58% in the year through July. That is roughly $410 billion less demand for the world's benchmark safe asset, arriving while Washington keeps issuing more debt.
The detail that matters is where the money went instead. Over the same twelve months, foreign investors made a record $942 billion in net purchases of US equities and investment fund shares. So global capital did not leave the United States. It rotated. It walked past the government bond desk and bought growth instead.
Foreign central banks tell the same story more quietly. Their Treasury holdings shrank by $13 billion in July, $67 billion over the year, and $587 billion since the 2015 peak. This is a slow reallocation, not a panic exit.
The backdrop is a debt load that keeps climbing. America's debt-to-GDP ratio sits at roughly double Germany, the Netherlands and the Scandinavian countries, and it is still rising fast. Italy and Greece, the usual cautionary tales, are steady or improving.
The Congressional Budget Office (CBO) sees the total deficit running 4.9 percentage points larger by 2056, reaching 14% of GDP. That is a structural gap, not a one-year bump.
Bitcoin barely twitched on the news, trading near $84,548. That fits. This is a story about the plumbing of the bond market, and plumbing rarely makes for a dramatic candle. It makes for a trend.
From deficits to crypto liquidity
The mechanism here is simple and patient. When fewer foreign buyers show up for US Treasuries, someone else has to be tempted in. The usual lure is a higher yield.
Higher Treasury yields do not stay in one lane. They pull mortgage rates and corporate borrowing costs up with them, because so much global pricing keys off the US government curve. That creates a second problem for Washington. A government running a deficit near 14% of GDP has to refinance constantly, so a higher yield means a bigger interest bill, which widens the deficit further. It is a loop that feeds itself.
Here is the read, framed honestly as our analysis rather than confirmed fact. If the Treasury market ever seizes up under that pressure, the Federal Reserve tends to supply liquidity before it allows a funding accident. It has chosen that path in every recent stress episode.
More liquidity and a softer dollar are the classic conditions under which scarce, hard-to-debase assets attract a bid. Bitcoin's fixed supply is the entire pitch in that world.
None of this is a same-day trigger. The confirmed facts are the falling demand and the record equity inflows. The Fed response is a probability we are weighing, not an event that has happened. That distinction matters. This is a structural tailwind that builds over months, not a catalyst you trade on the hour it prints.
Where the rotating capital lands
Read through this lens, the immediate market impact on crypto is muted, and that is the correct reaction. The confirmed shift is foreign money leaving Treasuries for US stocks, not flooding into Bitcoin.
BTC traded near $84,548 and ETH near $2,709 as this landed, gains under one percent on the day. There is no clean line from a bond-demand statistic to a crypto candle in a single session.
The transmission runs slower than that. First it shows up in the long end of the Treasury curve, where softer demand meets heavy supply and yields drift higher. That pressure eventually forces a policy choice. A market betting on future Fed liquidity is really betting the central bank blinks before the bond market breaks.
For Bitcoin, that expectation is the medium-term tailwind, because BTC is the most liquid expression of the debasement trade. When it moves, it moves first and leads.
Ethereum tends to follow BTC's lead with a lag and more force once the direction is set. Alts sit at the end of that queue, needing BTC stability before speculative capital rotates down the risk curve.
For now, none of that queue is firing on this news. The story sets the stage; it does not ring the bell. Treat it as a reason the floor may firm over quarters, not a reason to chase a move today.
Signals that confirm the liquidity thesis
The cleanest confirmation of this thesis is not a crypto chart at all. It is the long end of the US Treasury market. If yields keep grinding higher on weak auctions and thin foreign demand, the pressure on Washington's interest bill is real and building.
Watch the dollar alongside it. A softer dollar as yields rise is the tell that markets are pricing debasement rather than healthy growth, and that is the mix that historically favors Bitcoin.
The strongest signal would be any move by the Fed toward supplying liquidity into bond-market stress. That is the event this whole chain is waiting on.
What would invalidate the tailwind is just as important. If foreign buyers quietly return, or growth stays strong enough that yields rise without stress, there is no funding accident and no forced Fed hand.
A genuinely stronger dollar would also cut against the thesis, tightening liquidity rather than easing it.
On the crypto side, we are honest that the current price action is not driven by this news. So the near-term levels are set by market structure, not by the debt story.
The patient watch item is whether dips keep getting bought over the coming quarters. That behavior, more than any single headline, would show smart money treating scarce assets as the hedge against a bond market the world is slowly stepping back from.
Scarce assets in a deficit-driven regime
The ParadiseTeam separates this cleanly: the debt story is a slow structural tailwind, while the near-term chart is its own machine. Both can be true, and confusing them is how traders get chopped.
Our standing macro view stays cautious. We still expect crypto to work through a wider range, with a possible push toward the $88,000 to $90,000 zone before real resistance appears, and a deeper reset toward the $55,000 to $44,000 exchange of hands area remains on the table.
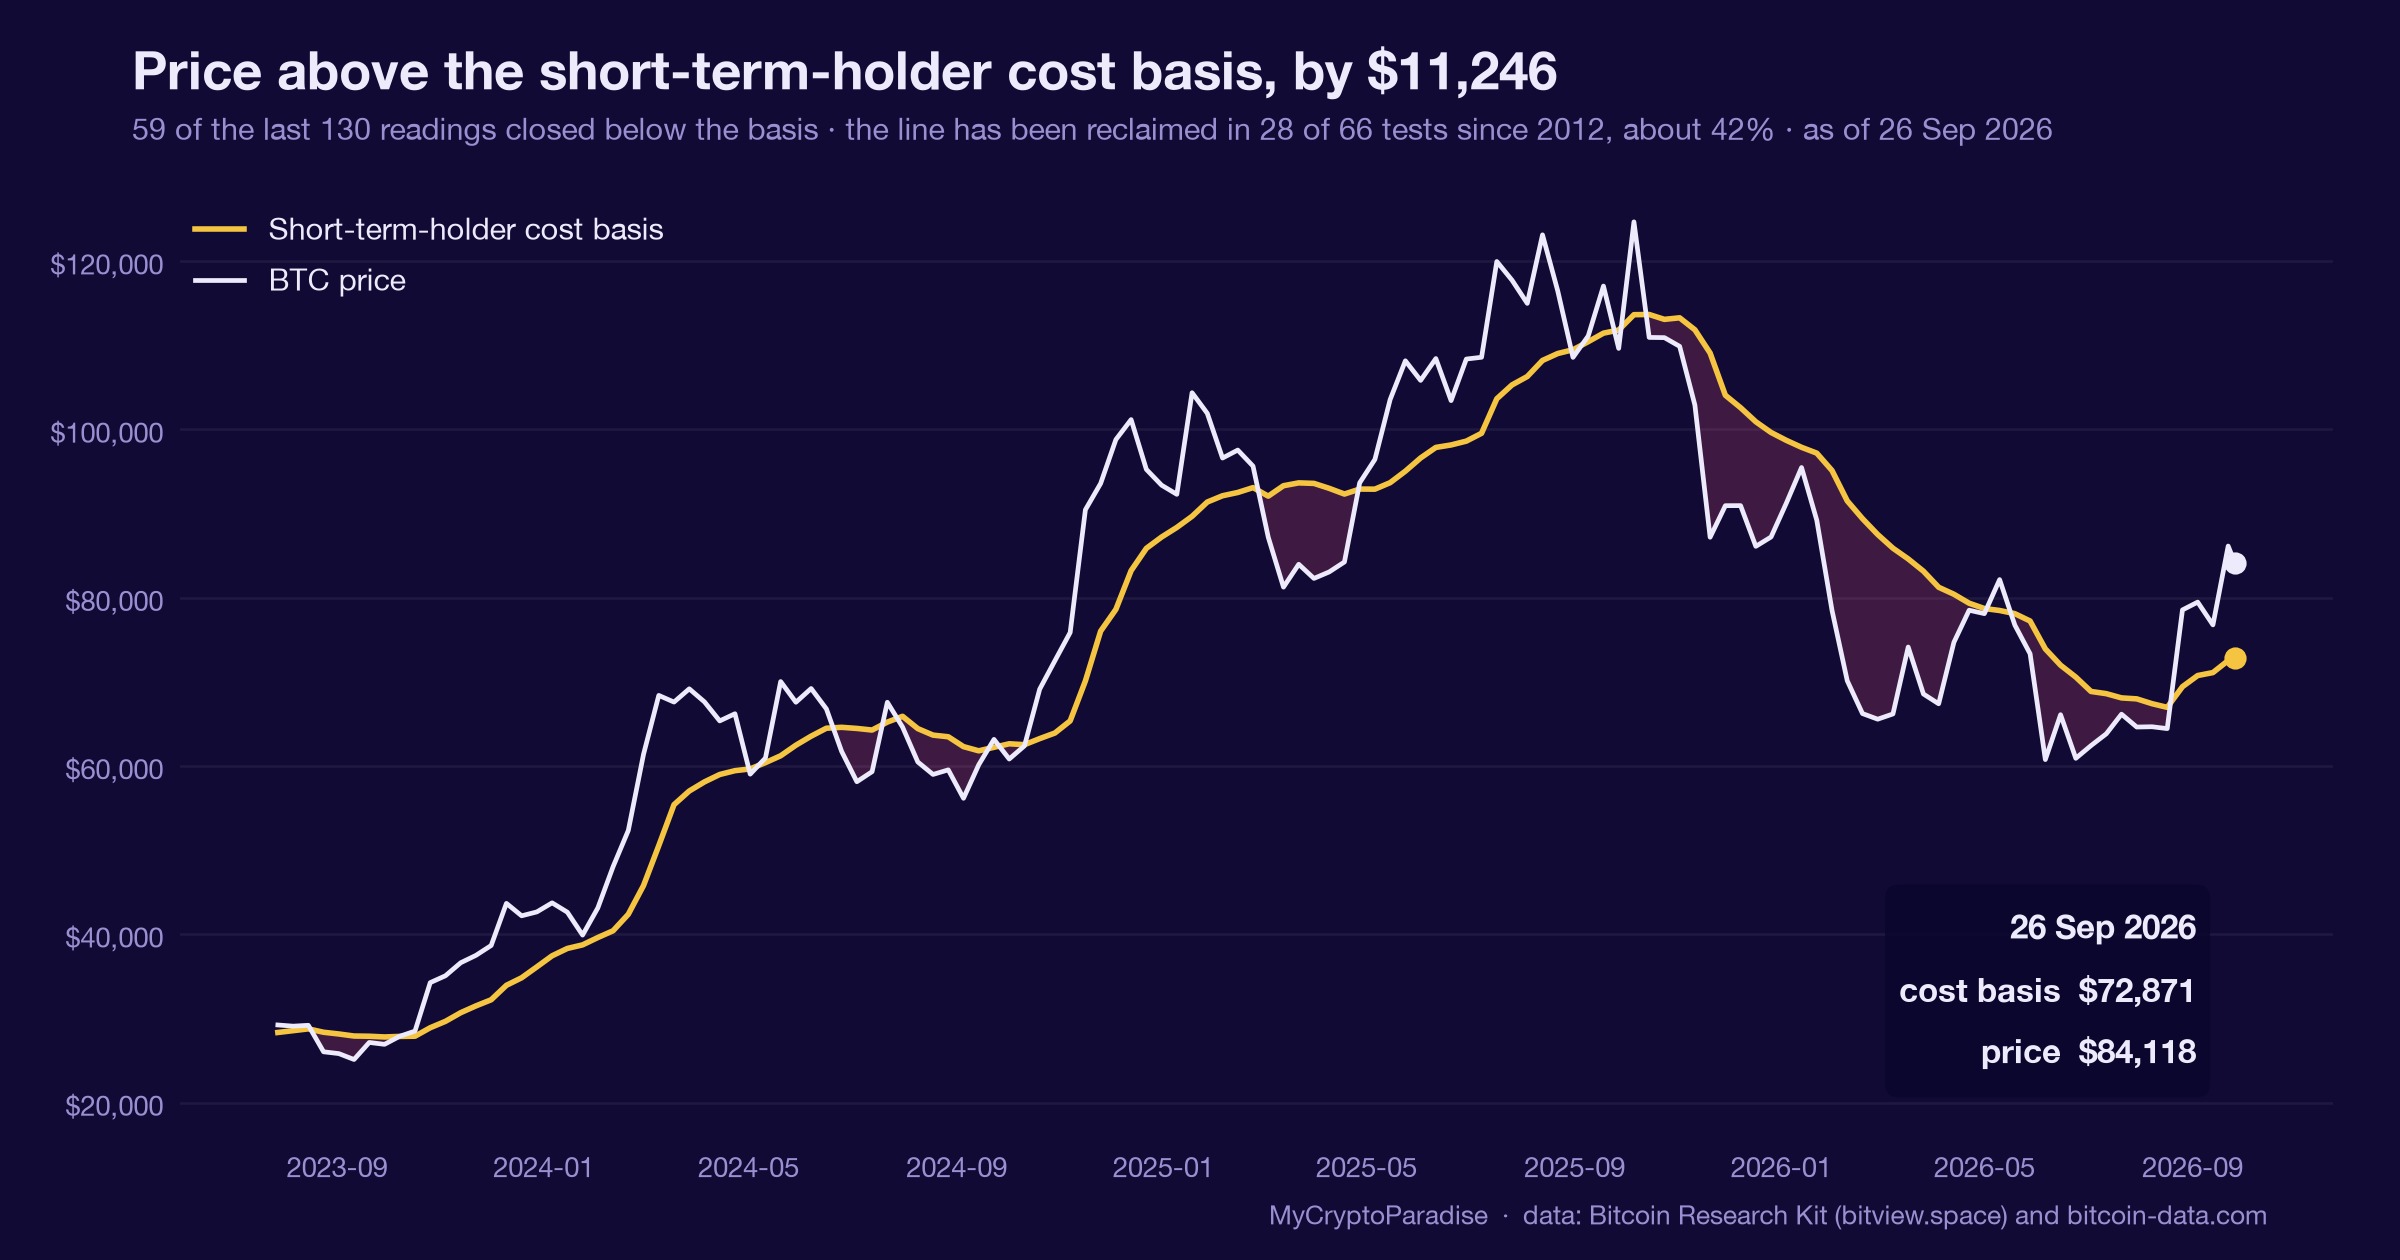
With BTC near $84,548, the level that matters most right now is $82,000. Reclaiming and defending it as support is the structural green light; losing it reopens the downside.
Here is how the debt story fits that map. It does not change any level on the chart. It changes the character of the eventual bottom, because a world drifting away from Treasuries is a world where scarce assets get accumulated on weakness, not chased on strength.
Retail tends to get this backwards. Interest spikes on the pumps and vanishes on the flushes, which is precisely when the patient buyer is most interested. So we frame it this way. Treat the falling Treasury demand as a reason to respect the long-term floor under Bitcoin, not as a signal to lever into today's candle. The macro tailwind rewards patience; the chart still demands discipline around $82,000.
The read behind this: we framed this story through our own market analysis, Can Bitcoin Push to $99K?
Track it live: our live crypto funding rates and the Crypto Fear and Greed Index both update in real time, so you can watch this shift for yourself.
Related coverage
For exact entries, targets, and stop losses with full risk management, that is what ParadiseFamilyVIP is for. New to reading these moves? Start with our crypto trading strategies guide.
ParadiseTeam is monitoring the market situation closely, and we are taking these developments into consideration while building our trading tactics inside ParadiseFamilyVIP.
Crypto trading involves substantial risk. Prices are volatile and you can lose money. This article is educational and is not financial advice. Past performance does not guarantee future results.

Join the discussion 4
its about the levels though right at the end of the day whats the one level that matters
i watch what the fed does with its own balance sheet too that tells you more sometimes
theyll just print more 💸 and bail out the banks again too, like always, leaving the rest of us to pick up the tab 😡🤬 it's a joke at this stage.
wow, this really makes sense with the inflation we had here. thank you for explaning it so clearly, i appreciate it a lot!