

Listen: the breakdown
Market briefing: MSCI confirmed Strategy leaves its USA Index at the November 30 close, with up to 8.8 billion dollars in forced passive selling on the table. BTC sat near 74,337 dollars, barely moving on the news.
- MSCI removes Strategy from its USA Index at the close of November 30, formally effective December 1.
- JPMorgan estimates 2.8 billion dollars in forced passive selling, rising toward 8.8 billion if other providers follow.
- BTC near 74,337 dollars barely moved; the pressure sits on MSTR shares, not the bitcoin treasury.
MSCI will remove Strategy from its USA Index at the November 30 close, forcing index funds to sell billions. But does deleting a bitcoin-treasury proxy actually move BTC?
MSCI confirmed it in its November review. Strategy, the company once known as MicroStrategy, leaves the MSCI USA Index at the close of trading on November 30. The change formally takes effect on December 1.
The reason is a new rule. MSCI now screens out firms it treats as non-operating companies, and a corporate bitcoin treasury the size of Strategy's fits that definition neatly. Once the deletion takes effect, passive funds that track the index must sell the stock. They do not get a vote.
JPMorgan put a number on it. Forced passive selling could reach 2.8 billion dollars from the MSCI change alone. If other index providers adopt the same logic, that figure could climb toward 8.8 billion. A dated, quantifiable forced seller is now circled on the calendar.
Strategy saw this coming. It has opposed the rules since they were first proposed last year, calling them discriminatory against digital assets. Saylor argued that index classification does not define the company. The index committee was not persuaded.
The firm spent years building its identity as the market's cleanest listed bitcoin proxy. The index has now decided it is less an operating business and more a holding vehicle, which is roughly the thing Strategy kept telling everyone it was.
A dated forced seller lands on MSTR
This is an equity-market mechanic, not a crypto headline on its surface. Index deletion forces index-tracking funds to sell at month-end. That selling is price-insensitive. It happens because a rule demands it, not because anyone judged the shares expensive.
Here is the bridge to crypto. Strategy is the market's most visible listed bitcoin proxy. For many equity investors, owning the stock meant owning bitcoin exposure inside an ordinary brokerage account. When forced selling hits that proxy, it chips at one channel of demand that has long fed the bitcoin story.
The chain is indirect but real. Weaker MSTR demand means a weaker equity bridge into bitcoin. Crucially, it does not force Strategy to sell a single coin, and nothing in the confirmed facts says it will. The pressure sits on the shares, not on the treasury.
That distinction matters. An equity overhang is not the same thing as spot supply arriving on crypto exchanges.
Still, the second-order effect leans negative. A mechanical seller in the most watched bitcoin-linked equity dents sentiment at a delicate moment. Retail often reads MSTR as a bitcoin thermometer. A falling thermometer rarely recruits fresh buyers.
Equity outflows versus the quiet spot tape
BTC was trading near 74,337 dollars as of the brief, up about 1 percent on the day. The spot tape barely acknowledged the MSCI news. The 1-hour move sat near flat. So the immediate crypto reaction is muted, which fits an equity-structure event.
The risk is slower and dated. The forced selling lands at the November 30 close, not today. Markets can drift toward a known flow event. If equity desks front-run the rebalance, MSTR can bleed into month-end, and that weakness tends to leak into crypto sentiment before it leaks into price.
BTC sets the tone from here. If the bitcoin proxy sells off into the deletion, BTC loses a supportive narrative at the margin. ETH typically follows BTC's risk appetite in these moments, with no direct MSCI link of its own. The read-through to Ethereum is sentiment, not mechanics.
Alts sit furthest down the chain. They carry the highest beta to BTC and the thinnest liquidity. If BTC softens into month-end on a weaker equity bridge, alts usually feel it harder and later.
None of this is forced crypto selling. It is a drip, not a flush.
November 30 close sets the clock
The date is the anchor. The November 30 close is when passive funds must complete the deletion. Watch MSTR volume and price into that window. Heavy, price-insensitive selling into month-end would confirm the flow is real and sizeable.
Watch whether other index providers follow. The 2.8 billion dollar estimate assumes MSCI acts alone. The path toward 8.8 billion needs others adopting the same non-operating screen. Each additional provider deepens the overhang and widens the dated selling window.
The key tell for crypto is correlation. If BTC begins tracking MSTR weakness tick for tick, the equity event is bleeding into spot. If BTC keeps ignoring the stock, as it largely did on the announcement, the overhang stays contained to equity.
The cleanest invalidation would come from Strategy itself. Any confirmed sign it is adjusting its bitcoin treasury in response would change this story entirely. Nothing in the facts points that way. Until that appears, treat this as an MSTR problem, not a BTC one.
Watch the proxy. Let it tell you whether this stays an equity story.
Why an MSTR overhang is not a BTC catalyst
The ParadiseTeam frames this as an equity overhang first and a crypto question second. BTC was near 74,337 dollars as of the brief. That sits below the 76,000 dollar level, which we treat as reclaimed-from-below resistance after support broke on the fourth touch.
On the daily timeframe, our standing bias stays lower. The structure points toward the 69,000 to 64,000 dollar support zone, with 69,000 the upper boundary and the level that matters most. The MSCI flow does not create that path. It simply removes one more reason for buyers to lean against it.
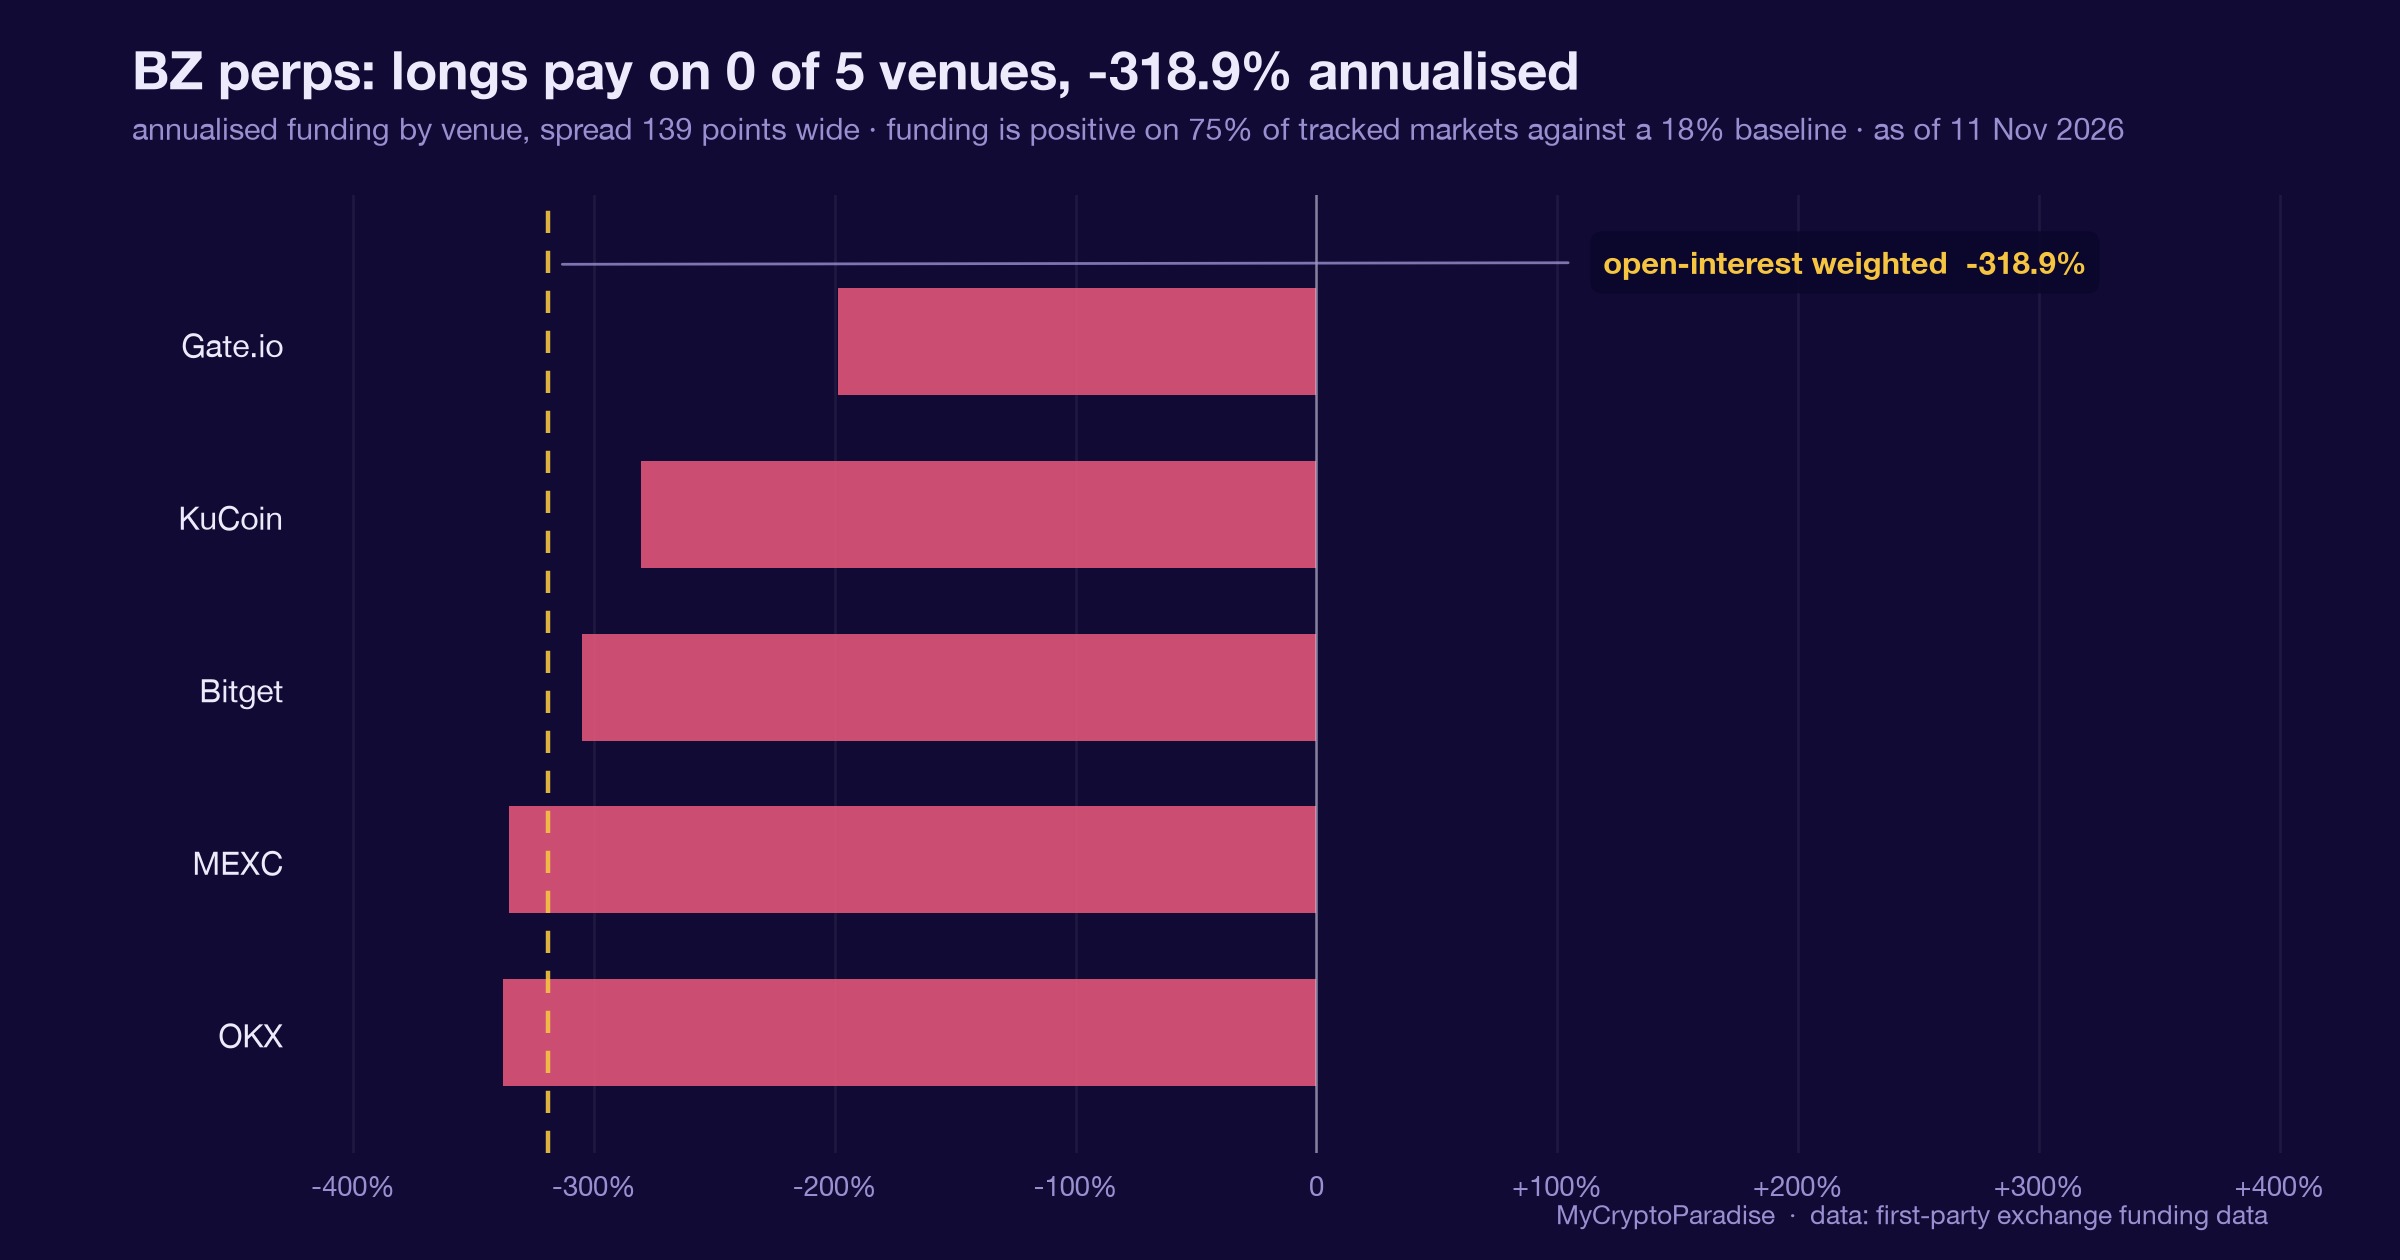
Here is the smart-money angle. Retail still crowds the long side, with funding elevated near plus 10 percent. Any bounce that stalls under 76,000 on thin volume looks like strength being sold into, not accumulation. A dented bitcoin proxy hands that distribution a convenient cover story.
Confirmation of our caution would be BTC rejecting 76,000 again, then losing 69,000 on real volume. A bullish momentum cross from oversold would soften the read. We do not have one yet.
The MSCI event is MSTR's problem on paper. The leverage sitting in crowded longs is crypto's.
The read behind this: we framed this story through our own market analysis, Bitcoin to $69K or Back Above $76K?
Track it live: our live crypto funding rates and the Crypto Fear and Greed Index both update in real time, so you can watch this shift for yourself.
Related coverage
For exact entries, targets, and stop losses with full risk management, that is what ParadiseFamilyVIP is for. New to reading these moves? Start with our crypto trading strategies guide.
ParadiseTeam is monitoring the market situation closely, and we are taking these developments into consideration while building our trading tactics inside ParadiseFamilyVIP.
Crypto trading involves substantial risk. Prices are volatile and you can lose money. This article is educational and is not financial advice. Past performance does not guarantee future results.
Will MSTR's index removal drag on BTC before the November 30 close?
How 1 Paradiser is calling it
The first call is still open
Free account, no password. Members just sign in.


Join the discussion
No comments yet. Members, share how you are reading this.