
In short
Funding is the recurring fee that leveraged traders pay to hold a perpetual futures position: when longs pay shorts, the crowd is leaning long. On 23 October 2026, a $13 billion Treasury auction revived the case for owning Bitcoin over fiat, and our MCP Insights funding data shows that trade is already consensus. Bitcoin longs are paying shorts 9.9 percent annualized, which our own tape labels mild long crowding, not euphoria. Gold perpetuals are hotter still at 48 percent, the single most long-paid market we track. We called this neutral: a crowded lean is not a top, and 9.9 percent is not extreme. No calibrated base rate is wired, so we claim no historical frequency here. This piece shows you how to read funding yourself, and why a sound macro thesis and a crowded tape are two different things.
Key facts
- Funding on BTC perpetuals
- +9.91% annualised, open interest weighted
- Positioning regime
- mild long crowding
- Markets where longs are paying
- 79% of those we track
- BTC price at the reading
- $81,256
- Open interest behind it
- $30.95B
- What would prove this read wrong
- Bitcoin funding accelerating well past the current 9.9 percent annualized into a genuinely crowded regime (loading real downside flush fuel), or draining back toward zero as longs step aside (removing the lean entirely).
- Reading taken
- 23 October 2026
- Source
- Our MCP Insights tools, from our own MCP Insights first-party data
Funding is a fee, not a forecast
A perpetual futures contract never expires, so exchanges use a funding payment to tether it to spot. When more traders want to be long than short, longs pay shorts, and the fee rises until the imbalance costs enough to correct it.
That makes funding a positioning gauge, not a direction. It tells you who is leaning which way and what they are paying to keep leaning, which is a measure of crowd conviction and crowd cost at once.
A fee that rises with crowding is the market charging admission to consensus. The higher the toll, the more it is worth asking whether the trade is still early.
The hard-money bet is already on the tape
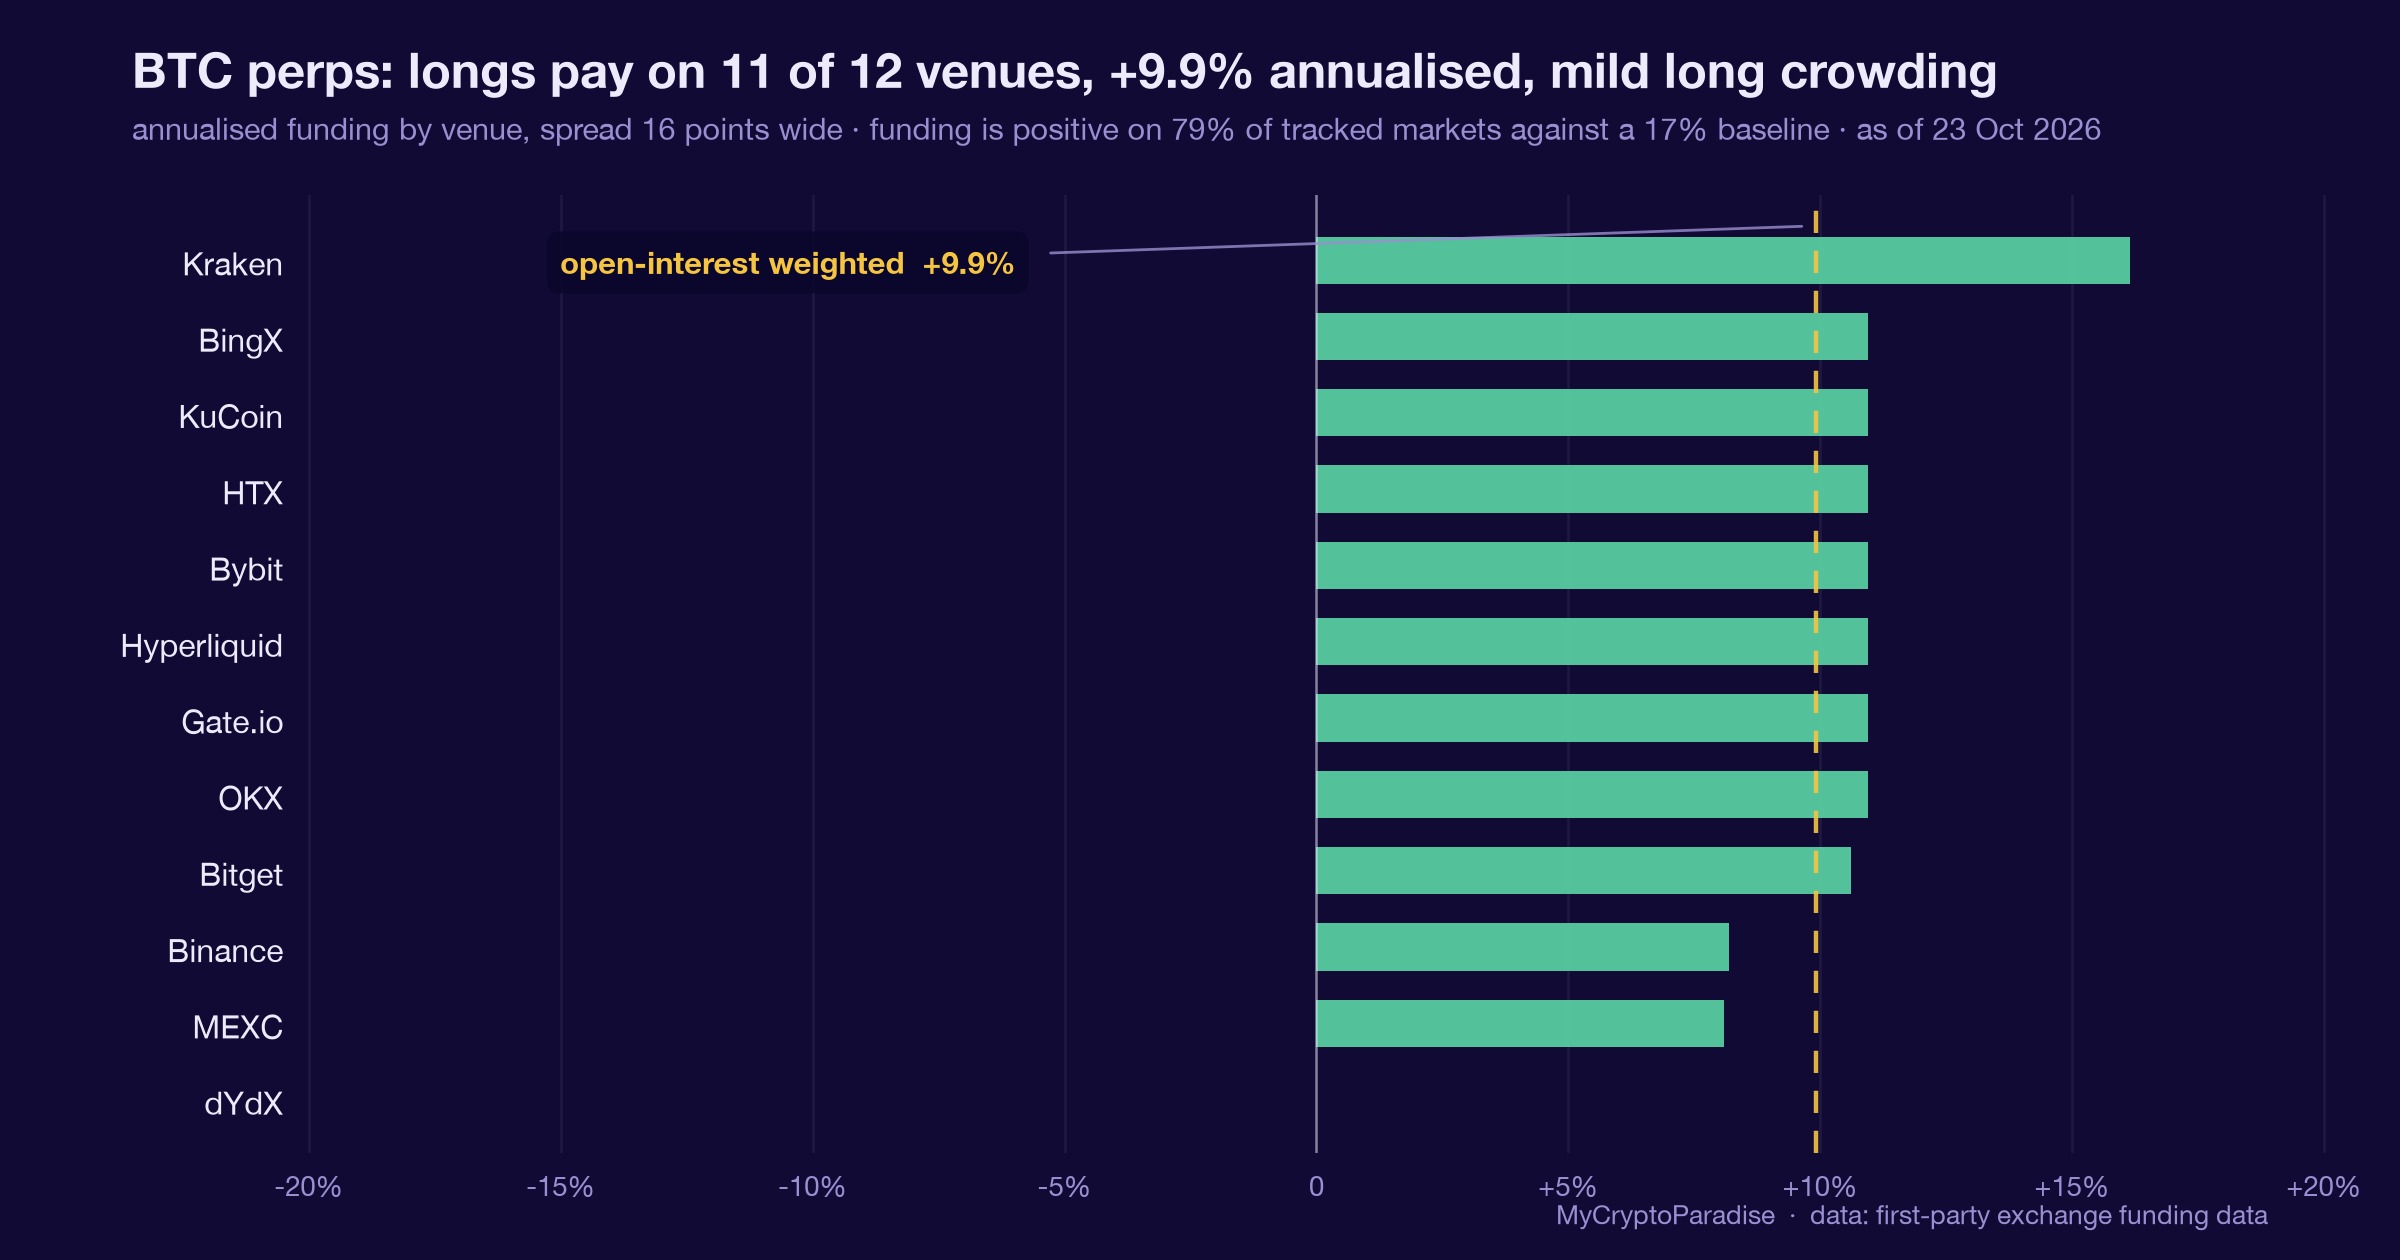
Per our MCP Insights funding data on 23 October 2026, Bitcoin trades near $81,256 with open interest (OI) of about $30.9 billion, and longs are paying shorts 9.9 percent on an annualized percentage rate (APR) basis. Our tape labels that mild long crowding.
The lean is broad, not isolated. Funding is positive on 79 percent of the markets we track, the median sits at 7.25 percent APR, and Ethereum runs a cooler 6.1 percent. Spot-to-futures basis is a flat minus 0.038.
The extreme lives elsewhere. Gold perpetuals are the single most long-paid market on our grid at 48 percent APR, while the most short-paid is a small-cap at minus 38.9 percent.
Every one of those numbers points the same way: the bet against fiat is not a lonely one. It is the consensus, and consensus pays to hold its seat.
What is different here
The ParadiseTeam does not read a bond auction as a Bitcoin price call. We read the funding tape to ask whether the trade it implies is already crowded, measuring the carry longs pay rather than the narrative they cite, because a toll is harder to talk up than a thesis.
Crowded is not the same as wrong
The easy misread is that a crowded long means an imminent top. It does not. Mild long crowding at 9.9 percent APR is a lean, not the euphoria that marks exhaustion, and funding this warm can persist for weeks while price grinds higher.
The real tell is carry. Longs paying 9.9 percent annualized are financing a macro thesis out of their own pocket every eight hours, and that cost only matters if the spot bid stalls. While coins keep leaving exchanges and buyers absorb supply, the toll is just the price of conviction.
This is one input. It sits alongside spot flows, open interest and the cost-basis cohorts, and today it is the layer measuring how crowded an otherwise sound idea has become.
A crowded trade and a wrong trade look identical until the bid disappears. Funding tells you the toll, never the timing.
The thesis and the tape are two questions
The auction makes a fiscal argument: $13 billion of 20-year debt at a 5.469 percent yield locks in interest for two decades, and a government that prefers cheap funding to spending cuts tends to inflate. That case for hard assets is coherent.
But a coherent thesis and a good entry are different questions. Funding does not grade the macro; it grades how many people have already acted on it. When the answer is 79 percent of markets and gold at its most long-paid, the idea is priced as conviction, not discovery.
Being right about the destination tells you nothing about the toll on the road. The tape prices the crowd, and right now the crowd agrees with you.
Where the crowding tilts the risk
State the imbalance plainly. With 79 percent of markets long-funded and gold at 48 percent APR, the hard-money trade is crowded on the same side across assets. That concentrates the fuel for a long flush if the bid ever steps back.
It is a mild tilt, not a loaded trap. At 9.9 percent APR Bitcoin is warm, not hot, so the downside fuel is real but modest. The read stops being neutral if funding accelerates toward a genuinely crowded regime, or drains back toward zero as longs step aside.
The weight sits with the long crowd, which is a statement about who is exposed, not about where price goes next. The invalidation is what keeps that honest.
Reading the funding tape yourself, step by step
- Open our live funding rates and read the Bitcoin annualized percentage rate (APR): positive means longs pay shorts, negative the reverse.
- Check the regime label next to it: mild, neutral or crowded tells you how far the lean has run.
- Read breadth, the share of markets funded positive, to see whether the lean is Bitcoin-only or market-wide.
- Scan the extremes list for the most long-paid and short-paid markets, which shows where the crowd is most committed.
- Compare funding against spot flows and open interest before you size anything: one gauge is a lean, never a verdict.
The step skipped is breadth. A single hot coin is noise, but 79 percent of markets leaning the same way is the crowd showing its whole hand.
Every number above is checkable against the live data. Start with the live crypto funding rates, then cross-read the MCP Insights hub and the Crypto Fear and Greed Index.
Act and invalidate
| Scenario | What confirms it | What kills it |
|---|---|---|
| Crowded lean holds | Funding steady near 9.9% APR | Funding drains toward zero |
| Long flush | Bid stalls, longs liquidate | Spot keeps absorbing supply |
| Crowding turns euphoric | APR accelerates well past 9.9% | Breadth falls below half |
Posture: Neutral and patient. The crowding is mild, so the honest stance is to respect the lean without chasing it and to watch the carry for the moment it either cools or overheats.
Frequently asked questions
What does positive Bitcoin funding actually mean?
It means more leveraged traders are positioned long than short, so the longs pay the shorts a recurring fee. At 9.9 percent annualized on 23 October 2026, our tape reads that as a mild lean, not a crowded extreme.
Does crowded funding mean a top is near?
Not by itself. Mild crowding can persist for weeks while price rises. It raises the fuel for a sharp long flush only if the spot bid stalls, which is why the carry matters more than the headline rate.
Why mention gold in a Bitcoin funding piece?
Because the same hard-money thesis drives both. Gold perpetuals sit at 48 percent annualized, the most long-paid market we track, which shows the bet against fiat is crowded across assets, not unique to Bitcoin.
What would change this neutral read?
Two things. Funding accelerating toward a genuinely crowded regime would load real downside fuel, while funding draining back toward zero would drain the lean entirely. Either one moves the read off neutral in a clear direction.
Is funding enough to trade on its own?
No. Funding is one positioning gauge among many, measuring crowd conviction and its cost. It sizes a bias you already hold from spot flows, open interest and cost basis; alone it is a lean, never a verdict.
Crypto trading involves substantial risk and is not suitable for everyone. Nothing here is financial advice; it is education only. Never risk more than you can afford to lose.
The private Extras feed, where the funding rate, cross-market breadth and the long-paid extremes update intraday with their invalidation levels, is part of PRO Paradiser, the intelligence layer behind the ParadiseFamilyVIP strategies.

Join the discussion
No comments yet. Members, share how you are reading this.